'Bout ta' Bubble'?
Are we in a housing Bubble? And when will it pop? To answer the most recent question on everyones minds first we need to understand: What is a bubble? The nature of the word implies that it must burst? And in the truest sense that is correct.
"A bubble is an unsustainable period of house price growth generated by artificial demand, such as loose underwriting or speculative buying."
It is true, what we are seeing today in double digit home appreciation is not necessarily sustainable BUT it is NOT the same as a bubble. This trending topic sparked by Recent Research published by the Dallas Fed which claimed that "home prices are out of step with market fundamentals." It is important to note in the same paper they also stated, “Based on present evidence, there is no expectation that fallout from a housing correction would be comparable to the 2007-2009 global financial crisis in terms of magnitude, or macro-economic gravity. Among other things, household balance sheets appear in better shape, and excessive borrowing doesn't appear to be fueling the housing market boom.”
The graph below tracks home price appreciation since the end of World War II:
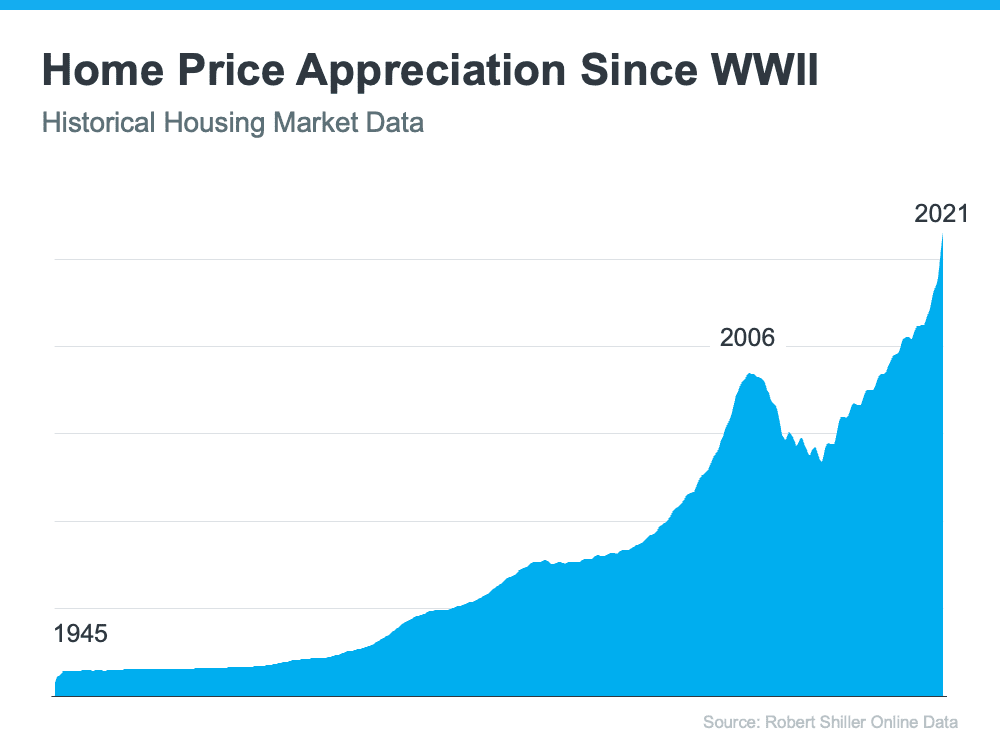
The graph shows the only time home values dropped significantly was during the housing boom and bust of 2006-2008. If you look at how prices spiked prior to 2006, it looks a bit like the current spike in prices over the past two years. That may lead some people to be concerned we’re about to see a similar fall in home values as we did when the bubble burst. To help alleviate those worries, let’s look at what happened last time and what’s happening today.
What Caused the Housing Crash 15 Years Ago?
Back in 2006, foreclosures flooded the market. That drove down home values dramatically. The two main reasons for the flood of foreclosures were:
- Many purchasers were not truly qualified for the mortgage they obtained, which led to more homes turning into foreclosures. Many purchased using “NO-Doc loans” which means there was much wider access to financing. In todays market it is harder to qualify for a conventional loan then even pre-pandemic, and the average credit score of borrowers in Q4 of 2021 was 778 which is much much higher than the housing boom.
- A number of homeowners cashed in the equity on their homes. When prices dropped, they found themselves in an underwater situation (where the home was worth less than the mortgage on the house). In order to trigger a foreclosure you need both a lack of equity as well as the inability to pay your mortgage. During these times many of these homeowners walked away from their homes, This lowered neighboring home values even more. This cycle continued for years.Today this is simply not the case. Home owners have historically record breaking amounts of equity in their homes. And if the situation were to arise where they were unable to pay their mortgage they could sell it (very quickly!) and walk away with the equity in their pockets and the loan paid off.
Why Today’s Real Estate Market Is Different?
Here are two reasons today’s market is nothing like the one we experienced 15 years ago.
- Today, Demand for Homeownership Is Real (Not Artificially Generated)
Running up to 2006, banks were creating artificial demand by lowering lending standards and making it easy for just about anyone to qualify for a home loan or refinance their current home. Today, purchasers and those refinancing a home face much higher standards from mortgage companies.
Data from the Urban Institute shows the amount of risk banks were willing to take on then as compared to now.
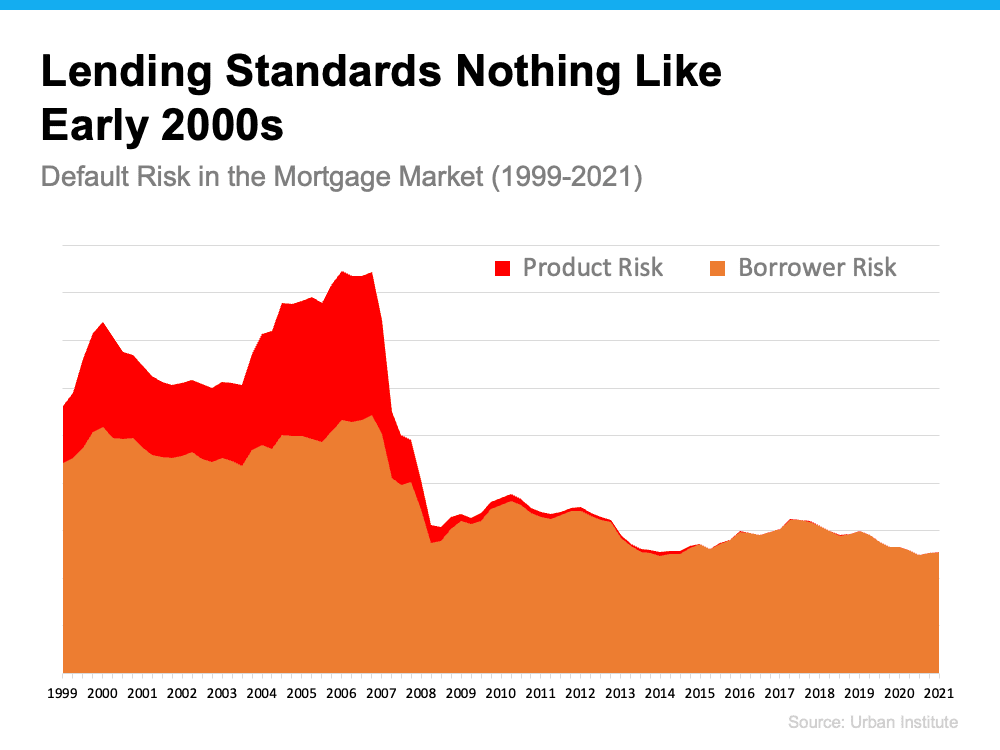
There’s always risk when a bank loans money. However, leading up to the housing crash 15 years ago, lending institutions took on much greater risks in both the person and the mortgage product offered. That led to mass defaults, foreclosures, and falling prices.
Today, the demand for homeownership is real. It’s generated by a re-evaluation of the importance of home due to a worldwide pandemic, as well as millennials aging into their prime home buying years and a lack of inventory from years of not keeping up with building. Additionally, lending standards are much stricter in the current lending environment. Purchasers can afford the mortgage they’re taking on, so there’s little concern about possible defaults.
And if you’re worried about the number of people still in forbearance, you should know there’s no risk of that causing an upheaval in the housing market today. There won’t be a flood of foreclosures. Most families have experienced a higher savings rate since the pandemic.
- People Are Not Using Their Homes as ATMs Like They Did in the Early 2000s
As mentioned above, when prices were rapidly escalating in the early 2000s, many thought it would never end. They started to borrow against the equity in their homes to finance new cars, boats, and vacations. When prices started to fall, many of these homeowners were underwater, leading some to abandon their homes. This increased the number of foreclosures.
Homeowners didn’t forget the lessons of the crash as prices skyrocketed over the last few years. Black Knight reports that tappable equity (the amount of equity available for homeowners to access before hitting a maximum 80% loan-to-value ratio, or LTV) has more than doubled compared to 2006 ($4.6 trillion to $9.9 trillion).
The latest Homeowner Equity Insights report from CoreLogic reveals that the average homeowner gained $55,300 in home equity over the past year alone. Odeta Kushi , Deputy Chief Economist at First American, reports: “Homeowners in Q4 2021 had an average of $307,000 in equity – a historic high.”
ATTOM Data Services also reveals that 41.9% of all mortgaged homes have at least 50% equity. These homeowners will not face an underwater situation even if prices dip slightly. Today, homeowners are much more cautious.
Bottom Line
The major reason for the housing crash 15 years ago was a tsunami of foreclosures. With much stricter mortgage standards and a historic level of homeowner equity, the fear of massive foreclosures impacting today’s market is not realistic. The effect of the federal governments Quantitative Easing programs are expected to moderate appreciation growth which is the goal. Rising rates and rising affordability will naturally slow the market, but as long as the demand out weighs the supply we will continue to growth. Specifically on the islands, I personally do not see supply and demand balancing out in the near future.
If you are entering the market during these times please REACH OUT. I love talking about economics, real estate, and would love to learn about how these concepts are affecting your unique home selling and buying goals. Together we can achieve anything :)